Remortgaging
Remortgage and rate-switch advice
When a mortgage deal ends, you usually move to the lender's standard variable rate, which can cost more. Reviewing your options in good time gives you more choice.
Advice by Charlene McGuire, mortgage and protection adviser with 25 years' experience, based in North Lanarkshire.
Your home may be repossessed if you do not keep up repayments on your mortgage.
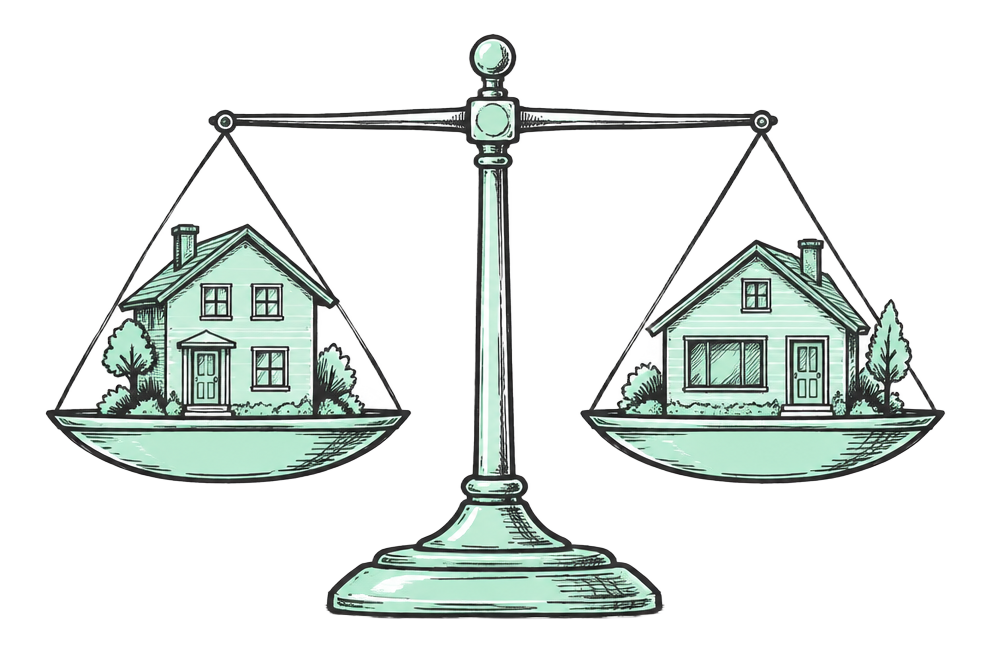
Staying or switching lender
A product switch with your current lender can be simpler, often without new legal work. Moving to another lender, a remortgage, may offer different options but involves new checks and possibly fees.
Neither is automatically better. The right choice depends on rates, fees, your circumstances and plans.
When to start
Many lenders let you secure a new deal several months before your current one ends. Starting early gives time to compare without rushing.
Borrowing more
Some people remortgage to release money for home improvements or other plans. Securing other debts against your home can increase the total you repay and puts your home at risk if you can't keep up repayments.
Product transfer or a new lender?
As a fixed rate nears its end, you can usually take a product transfer with your current lender or remortgage to a new one. A transfer is often simpler, with no new valuation or legal work; switching may open up other deals but can involve fees and legal costs. Comparing both on total cost, not just rate, gives the clearer picture.
Local remortgage advice
Charlene is based in Muirhead and Chryston in North Lanarkshire and advises clients across Moodiesburn, Gartcosh, Glenboig, Stepps, Cumbernauld, Coatbridge, Airdrie, Glasgow and surrounding areas. Appointments can be face to face locally, or by phone or video if that suits you better.
Common questions
When should I look at remortgaging?
Around three to six months before your deal ends is a sensible time to start, as many lenders let you reserve a deal in advance.
Will I pay a fee to leave my current deal?
If you leave during a fixed or discounted period, an early repayment charge may apply. Your mortgage documents show the amounts and dates.
What is a product transfer?
A new deal with your existing lender. It can be quicker, as there is often no new valuation or legal work, but it may not be the best option for you.
Can I borrow more when I remortgage?
Possibly, for example for home improvements. The lender will reassess affordability and the property value, and borrowing more increases the total you repay.
Will I need a valuation when I remortgage?
Usually, yes, but it's often simpler than when buying. Some lenders use an automated or 'desktop' valuation based on recent sales data, while others arrange a surveyor visit. Some remortgage deals include a free valuation as an incentive.
What happens if I do nothing when my deal ends?
You'll usually move onto your lender's standard variable rate, which is often higher than a fixed or tracker deal. There's no penalty for doing nothing, but reviewing your options a few months ahead gives you more choice.
Ready to talk it through?
Send an enquiry and Charlene will get in touch to understand your plans and explain what the next steps could look like.